R22 Prices Retreat as China's Refrigerant Market Faces Tight Quotas and Soft Demand




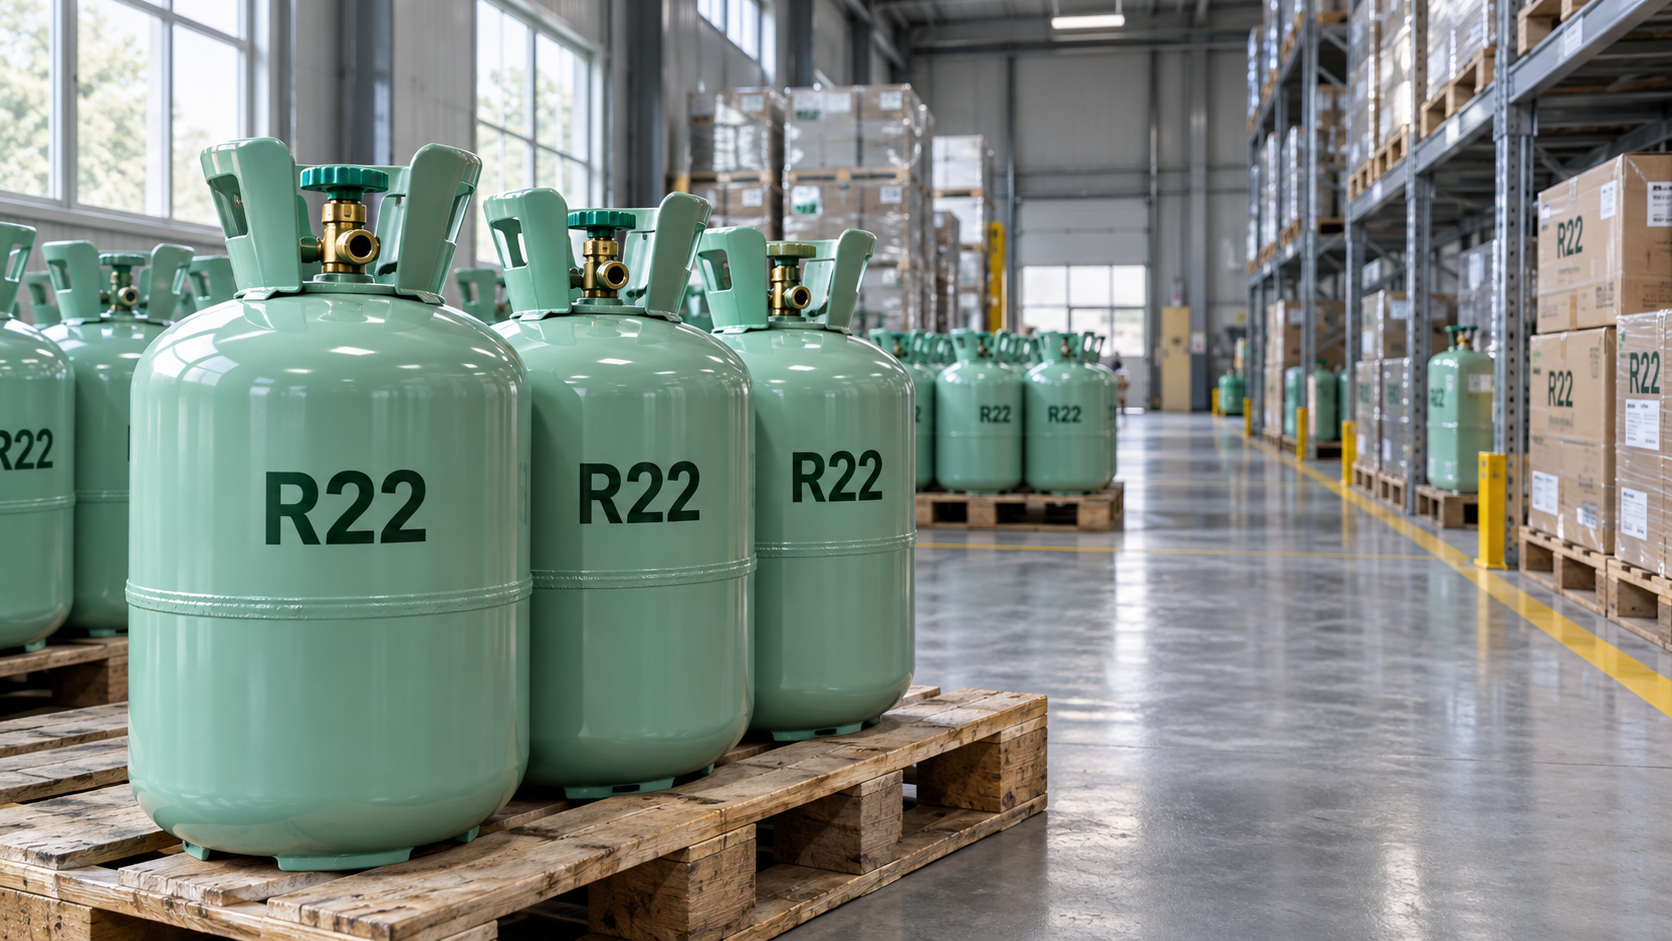
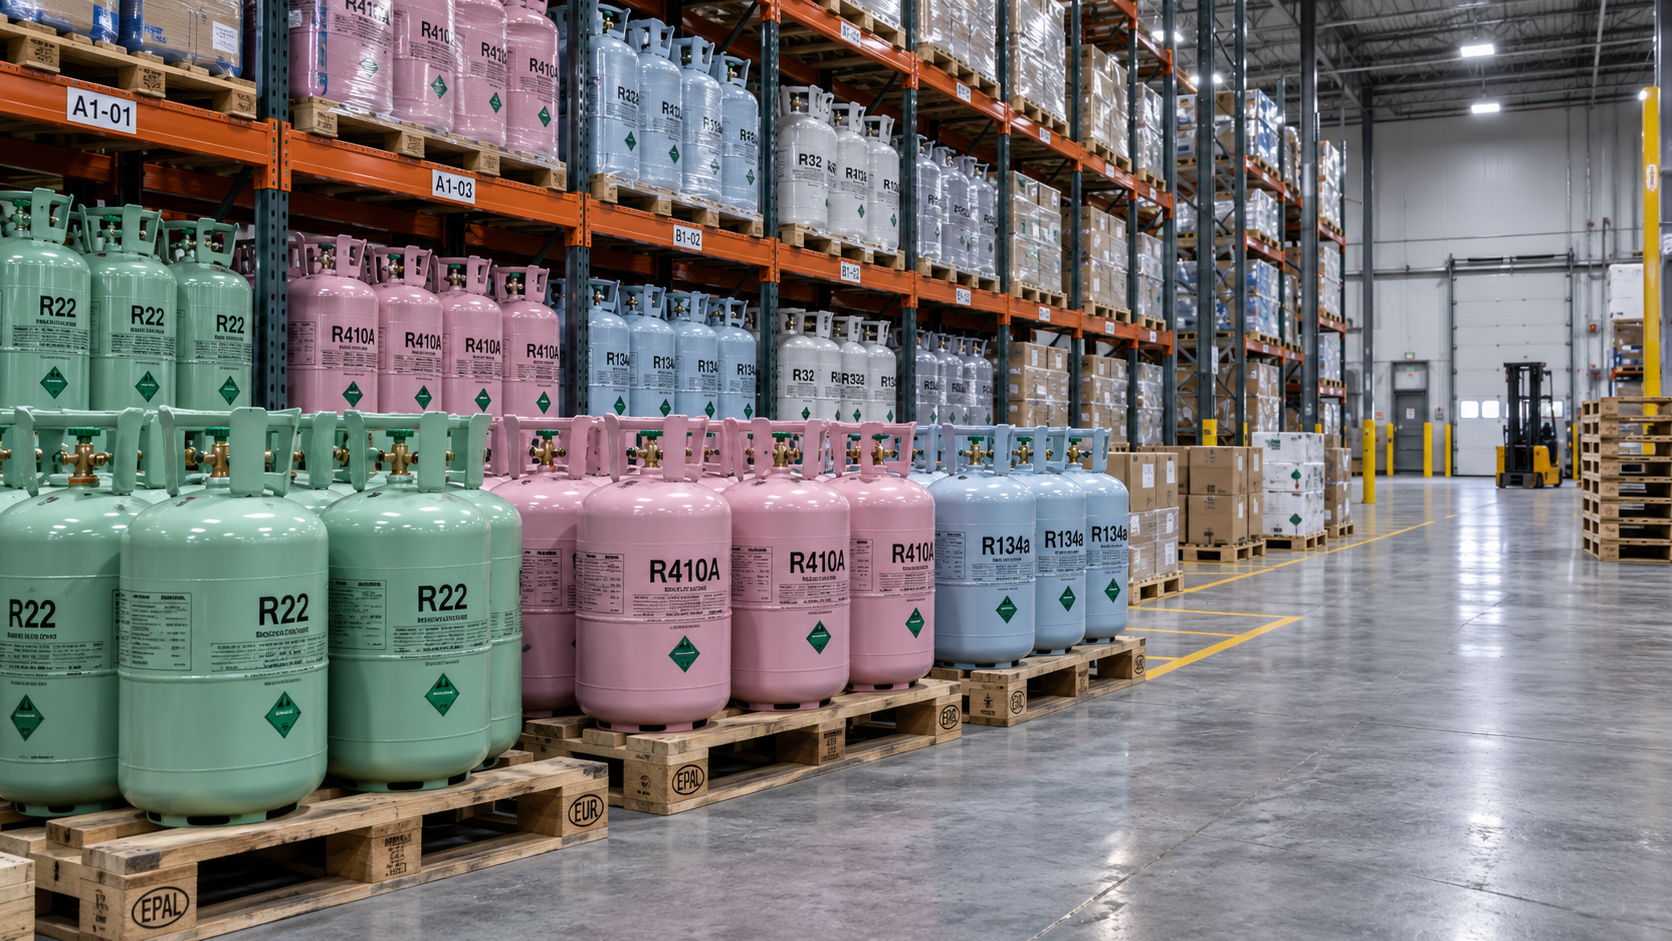
China's refrigerant market fluctuated at elevated price levels on October 21, 2026, with R22 leading the pullback. Its ex-factory price stood at RMB 19,500 per tonne, while R32 and R134a remained quoted at RMB 65,000 per tonne each. The divergence highlights a market in which tight supply constraints are meeting uneven demand.
The 2026 quota for third-generation refrigerants totals 797,800 tonnes, with the six largest companies holding more than 90% of the allocation. These limits constrain supply, but they do not guarantee that buyers will accept higher prices or maintain purchasing volumes.
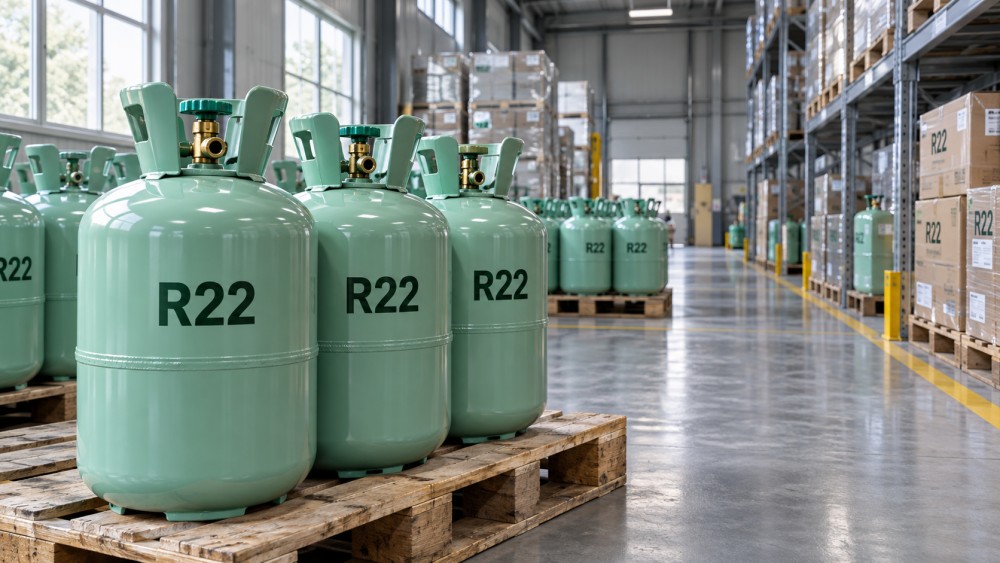
R22's decline points to demand pressure
R22 faces pressure from declining demand in its existing market and selling by traders. Together, these factors suggest that near-term purchasing needs and the volume offered for sale can weigh on prices even when the broader refrigerant market remains elevated.
The distinction between products matters. The quota figures concern third-generation refrigerants, while the reported pressures on R22 relate to its own demand and trading conditions. R22's retreat therefore does not, by itself, establish that R32 and R134a are entering a similar decline. Their unchanged quotations also do not establish stronger demand.
Purchasing decisions hinge on demand follow-through
For buyers, the immediate issue is whether current prices are supported by actual replenishment needs. Purchasing against confirmed requirements can limit exposure to a further correction while covering operational needs. The available market signals favor this approach over building inventory in anticipation of continued price increases.
The next development to watch is whether R22's selling pressure persists and whether demand for R32 and R134a can sustain their current quotations. Continued weak purchasing would test price support from constrained supply; firmer replenishment demand could help stabilize prices. For now, the evidence supports a cautious, product-specific assessment rather than a single price outlook for all refrigerants.
Ready when you are. Send us a message to get started.
Related News
- R22 Prices Retreat as China's Refrigerant Market Faces Tight Quotas and Soft DemandAuthor :Cryogenic Systems Expert

- Chemours Faces Investor Lawsuit Over Opteon Refrigerant Sales ForecastsAuthor :Cryogenic Systems Expert

- LG Expands R290 Monobloc Heat Pump Range with New 12–16 kW ModelsAuthor :Cryogenic Systems Expert

- EU Issues Updated Guidance on Industrial Refrigeration Efficiency and F-gas AlternativesAuthor :Cryogenic Systems Expert

- Do U.S. refrigerant regulations require replacing R-410A systems?Author :Cryogenic Systems Expert

- Where R-134a Restrictions Apply and How They Affect Refrigeration EquipmentAuthor :Cryogenic Systems Expert

- R-22 Phase-Out: Repair, Retrofit, or Replace Aging Commercial Cooling Systems?Author :Cryogenic Systems Expert

- R-410A Phase-Down Rules: Planning HVAC Replacements Before Supply TightensAuthor :Cryogenic Systems Expert

- Freon Policy Updates: What Facility Managers Must Review Before Equipment ServiceAuthor :Cryogenic Systems Expert

- How to verify refrigerant regulations and safety standards for a facilityAuthor :Cryogenic Systems Expert

- When refrigerant management software makes sense for multi-site complianceAuthor :Cryogenic Systems Expert

- EU Ends Duty-Free Small Parcels From July 1Author :Cryogenic Systems Expert

- China R410A Export Quotes Rise to RMB 60,000/TonAuthor :Cryogenic Systems Expert

- EU PFAS Curbs Raise Compliance Review for Cooling ExportsAuthor :Cryogenic Systems Expert

- EU PFAS Proposal Puts Refrigerant and Vacuum Exports Under ReviewAuthor :Cryogenic Systems Expert

- EU REACH PFAS Draft Raises New Export ChecksAuthor :Cryogenic Systems Expert

- EU Cuts High-GWP Refrigerant Import Quotas by 35%Author :Cryogenic Systems Expert

- EU Cuts Q4 2026 Quotas for High-GWP RefrigerantsAuthor :Cryogenic Systems Expert

- EU F-Gas Revision Cuts R410A Quotas 40%Author :Cryogenic Systems Expert

- EPA Freezes R-410A Quotas, Fast-Tracks R-32Author :Cryogenic Systems Expert

- Low GWP Refrigerants HFO Blends: Key Stability and Safety FactorsAuthor :Cryogenic Systems Expert

- R-32 Price Spike Reshapes Chiller ProcurementAuthor :Cryogenic Systems Expert

- How to Compare Environmentally Friendly Refrigerants by GWP, Safety, and CostAuthor :Cryogenic Systems Expert

- R-454B Export Quota Cut 18% as Lead Times DoubleAuthor :Cryogenic Systems Expert

- Japan Cuts R32 and R290 Import Quotas From July 10Author :Cryogenic Systems Expert

- EPA Cuts R-134a Import Quotas 42% From July 2026Author :Cryogenic Systems Expert
![]()
- Low GWP Refrigerants HFO Blends: Performance and Compliance in 2026Author :Cryogenic Systems Expert

- R-513A Jumps 23% as China Tightens Export QuotasAuthor :Cryogenic Systems Expert

- Environmentally Friendly Refrigerants in 2026: Compliance Risks and Upgrade PrioritiesAuthor :Cryogenic Systems Expert

- Pharmaceutical Temperature Control Systems: Common Compliance RisksAuthor :Cryogenic Systems Expert

- China Tightens Q3 R32 Export QuotasAuthor :Cryogenic Systems Expert

- California EPR Deadline Nears for Refrigeration MakersAuthor :Cryogenic Systems Expert

- Resource Circularity Trends Reshaping Refrigerants and Cooling SystemsAuthor :Cryogenic Systems Expert

- HFCs Filing Rules Enter Full EnforcementAuthor :Cryogenic Systems Expert

- How Environmentally Friendly Refrigerants Affect Chiller ComplianceAuthor :Cryogenic Systems Expert

- EU REACH Tightens Refrigerant Impurity Limits for R134a ExportsAuthor :Cryogenic Systems Expert